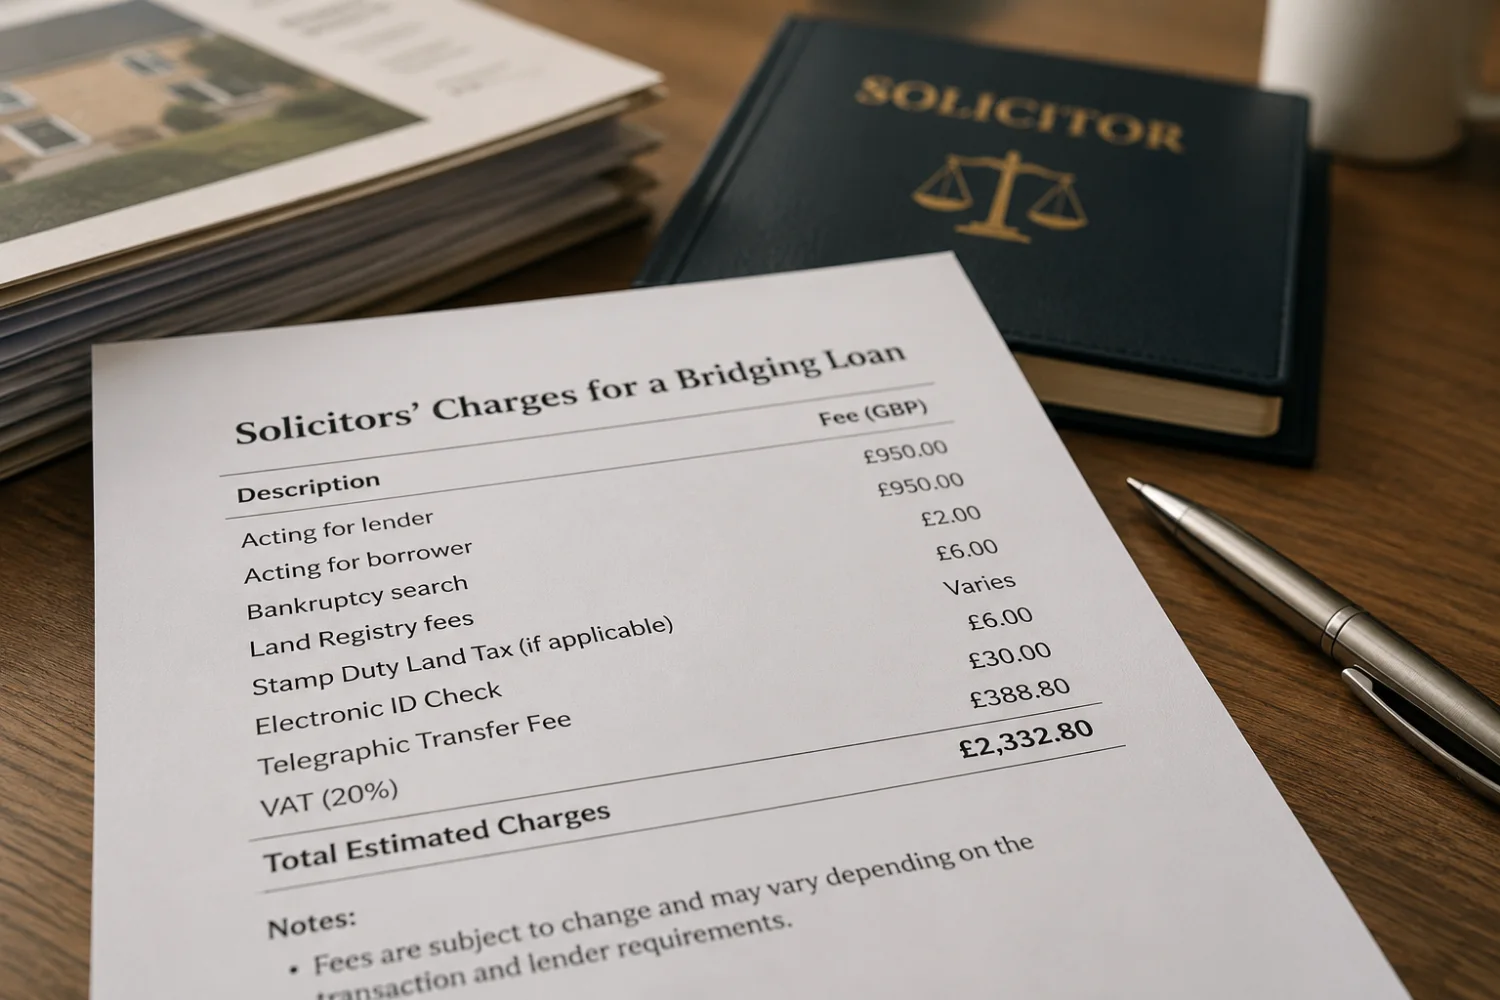
How much do solicitors charge for a bridging loan? For a straightforward residential bridge, a combined professional-fee budget for the borrower’s solicitor and, where separate representation is required, the lender’s solicitor can be in the low thousands. For budgeting only, the scenario table below uses an illustrative £1,500–£2,150 combined professional-fee range for a simple residential case before any VAT or disbursements not included in the quote. It is not a tariff or guarantee.
The final bill depends more on complexity, urgency, property and security structure, lender requirements and the scope of legal work than on the loan amount alone. This guide explains what a quote may include, when lender-side fees may be passed to the borrower, when dual representation may reduce duplication, and which costs should be confirmed in writing before you instruct a solicitor.
Why bridging loans often involve borrower and lender legal fees
A bridging loan is secured against property, so the lender needs legal due diligence around title, security and registration of its charge. In many transactions the borrower instructs one solicitor and the lender uses another firm, with the lender’s legal costs passed to the borrower under the loan terms. Where the lender permits dual representation and the solicitor can act in accordance with professional obligations, one firm may handle both sides of the legal work. The exact structure should be confirmed from the lender’s instructions and the solicitor’s written quote.
How much do solicitors charge for a bridging loan? Scenario guide
The examples below are budgeting illustrations, not market tariffs. Complexity and urgency usually matter more than the loan amount itself, and different firms and lenders price the same transaction differently.
| Scenario | Illustrative borrower solicitor fee | Illustrative lender solicitor contribution | Illustrative combined professional fees* |
|---|---|---|---|
| Simple residential bridge (single property, clean title, standard timeline) | £750–£1,200 | £750–£950 | £1,500–£2,150 |
| Auction purchase (tight 28-day completion deadline) | £1,200–£2,000 | £900–£1,200 | £2,100–£3,200 |
| Commercial or semi-commercial property | £1,500–£3,000+ | £1,000–£1,800 | £2,500–£4,800+ |
| Multiple properties or complex title (unregistered land, leasehold issues) | £2,000–£4,000+ | £1,200–£2,500+ | £3,200–£6,500+ |
*Illustrative budgeting figures only. VAT (where chargeable) and disbursements may be additional unless a quote expressly includes them. Actual fees vary by firm, lender requirements, property and title, borrower structure, urgency and transaction scope. Obtain a written, itemised quote before instructing.
What actually drives the price up or down
- Whether the title is registered and straightforward, or unregistered, leasehold, or affected by restrictive covenants
- How many properties are being used as security — each one can add to the title, search and registration work required
- Whether the deadline is tight — especially auction purchases, where compressed completion times can require priority handling
- Residential versus commercial or semi-commercial property, which can involve leases, occupational interests and additional due diligence
- Whether the lender permits dual representation, or requires a separate firm from its panel to act for the lender
Dual representation: can the same solicitor act for both sides?
Dual representation means one firm is instructed to act for both borrower and lender where the lender permits it and the solicitor is satisfied it can act. It can reduce duplicated work and may reduce overall legal costs, but it does not necessarily mean there is one flat fee or that lender-side work is free.
It will not be suitable or available in every case. Lender panel rules, conflicts, transaction complexity and the firm’s professional obligations all matter. A higher loan-to-value or more complex security may also lead a lender to prefer separate representation. If LTV is part of your planning, see our guide to how much deposit you need for a bridging loan.
Not sure whether dual representation applies to your case?
We can help you check the lender’s requirements and explain how the legal-fee structure is likely to work. Availability is lender- and case-specific, so it should be confirmed before you budget on the basis of one firm acting for both sides.
Get a Fee QuoteCommon professional work that may be included in the quoted legal fee:
- Reviewing and advising on the loan agreement, security documents and material legal risks
- Reviewing title and dealing with the agreed property searches and lender enquiries
- Completing and registering the lender’s legal charge at HM Land Registry
- Managing completion funds and carrying out the required client due-diligence and anti-money-laundering process
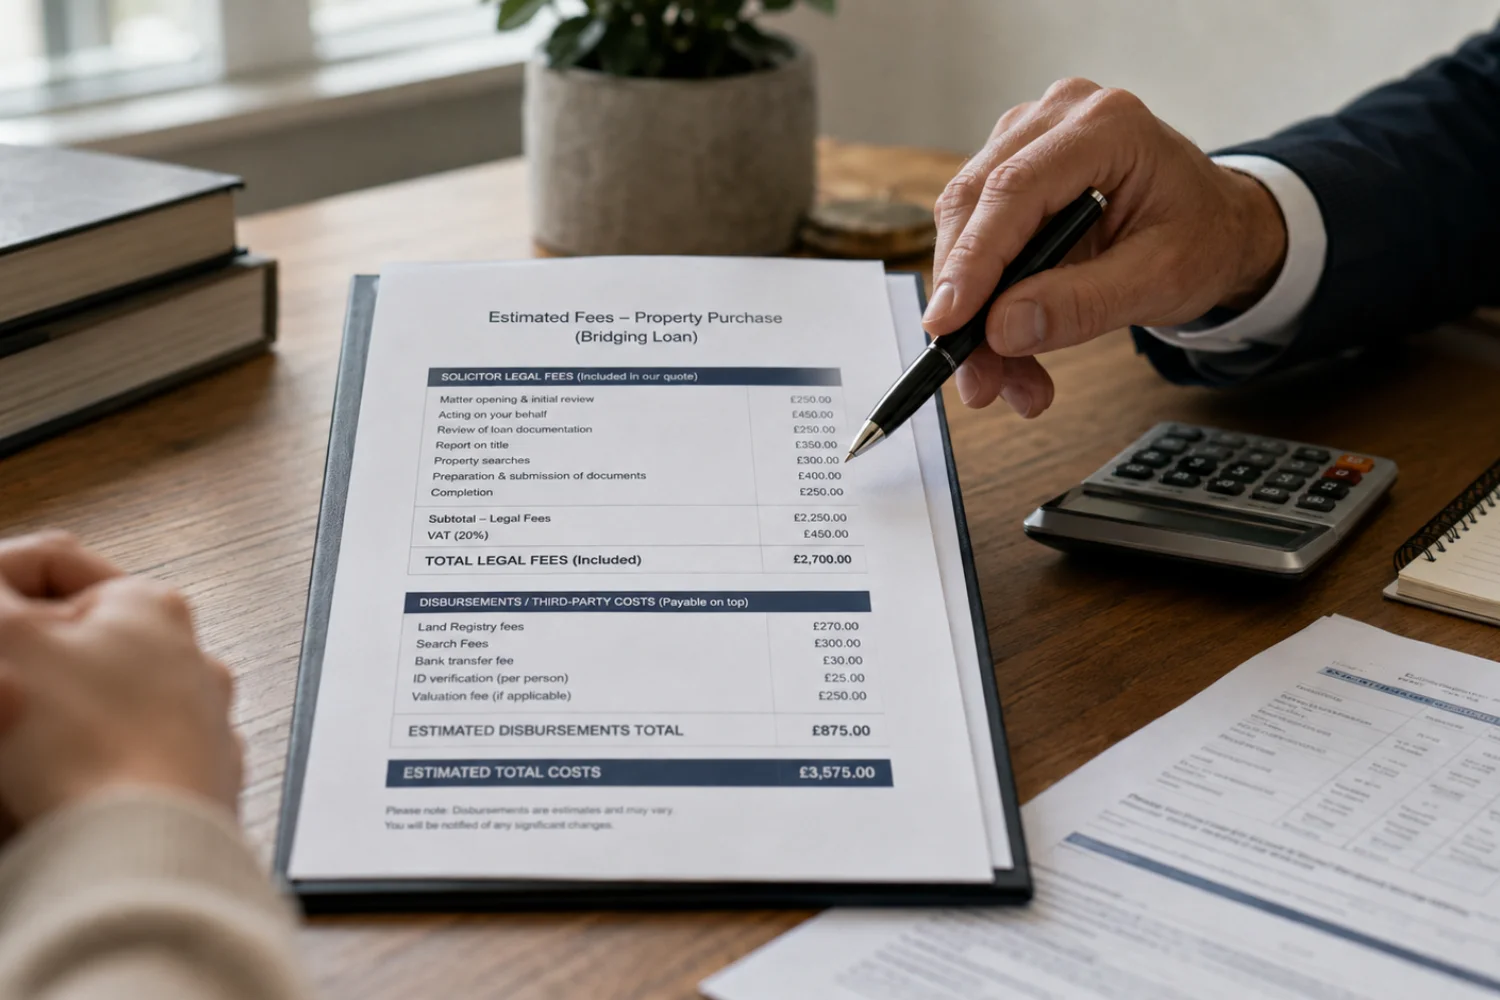
Common third-party disbursements that may be charged separately:
- HM Land Registry fees, official copies and priority/bankruptcy searches
- Property search fees, where local authority, drainage, environmental or other searches are required
- Indemnity insurance premiums, where a title issue requires an appropriate policy
- Bank transfer/CHAPS charges or other third-party verification/search charges, if separately itemised
The SRA Transparency Rules require SRA-regulated firms that publish specified services to provide clear price and service information for areas including residential conveyancing and mortgages/re-mortgages. Required information includes the total or a range/average, the charging basis, likely disbursements, VAT, what is included or excluded, and key stages and likely timescales. Whether a particular bridging matter falls within a mandatory publication category depends on the service offered, so a blog estimate should never replace an itemised written quote. Urgency or out-of-hours surcharges are normally additional professional charges rather than third-party disbursements.
How to avoid paying more than you need to
- Ask for a fixed or clearly itemised quote in writing and check whether it includes VAT, lender-side legal costs, disbursements and any supplemental charges
- Instruct a solicitor experienced in bridging finance early — avoidable delay can add borrowing cost while interest continues to run. For context, see our guide to current bridging loan interest rates.
- Ask directly whether dual representation is permitted by the lender and suitable for the transaction, rather than assuming it will be available
- Avoid last-minute instructions where possible — urgent work may attract an additional professional charge, particularly where completion deadlines are compressed
If you are budgeting beyond the legal bill, our full breakdown of bridging loan costs and fees explains how legal costs sit alongside interest, arrangement, valuation and other charges. You may also want our guide on whether you need a solicitor for a bridging loan before choosing who to instruct.
Frequently asked questions
Do I have to pay the lender’s legal fees as well as my own?
Often, yes where the lender uses separate representation: the loan terms commonly make the borrower responsible for the lender’s legal costs. If dual representation is permitted, the fee structure can be different. Check the lender’s offer and the solicitor’s written quote rather than assuming there will always be two separate bills.
Can I use my own conveyancer instead of a bridging loan specialist?
You can choose a conveyancer who is able and willing to handle the work, subject to any lender-panel requirements. Bridging transactions are time-sensitive, so relevant experience can matter. See our guide on whether you need a solicitor for a bridging loan for the practical considerations.
Are bridging loan legal fees negotiable?
You can ask for a written quote and compare firms, but compare scope as well as headline price. A lower quote may exclude lender-side fees, VAT, searches, Land Registry charges or extra work that another quote includes.
When do I need to pay the solicitor’s fees?
This varies by firm and transaction. A solicitor may ask for money on account before starting, especially for searches or other disbursements, with further fees due before or at completion. Confirm the payment timetable, VAT position and any non-refundable third-party costs in the written quote.
Ready to get a clear, written quote?
Speak to our team for a free, no-obligation consultation. We can explain the likely legal work and provide or arrange a clear fee quote based on the actual transaction before you commit.